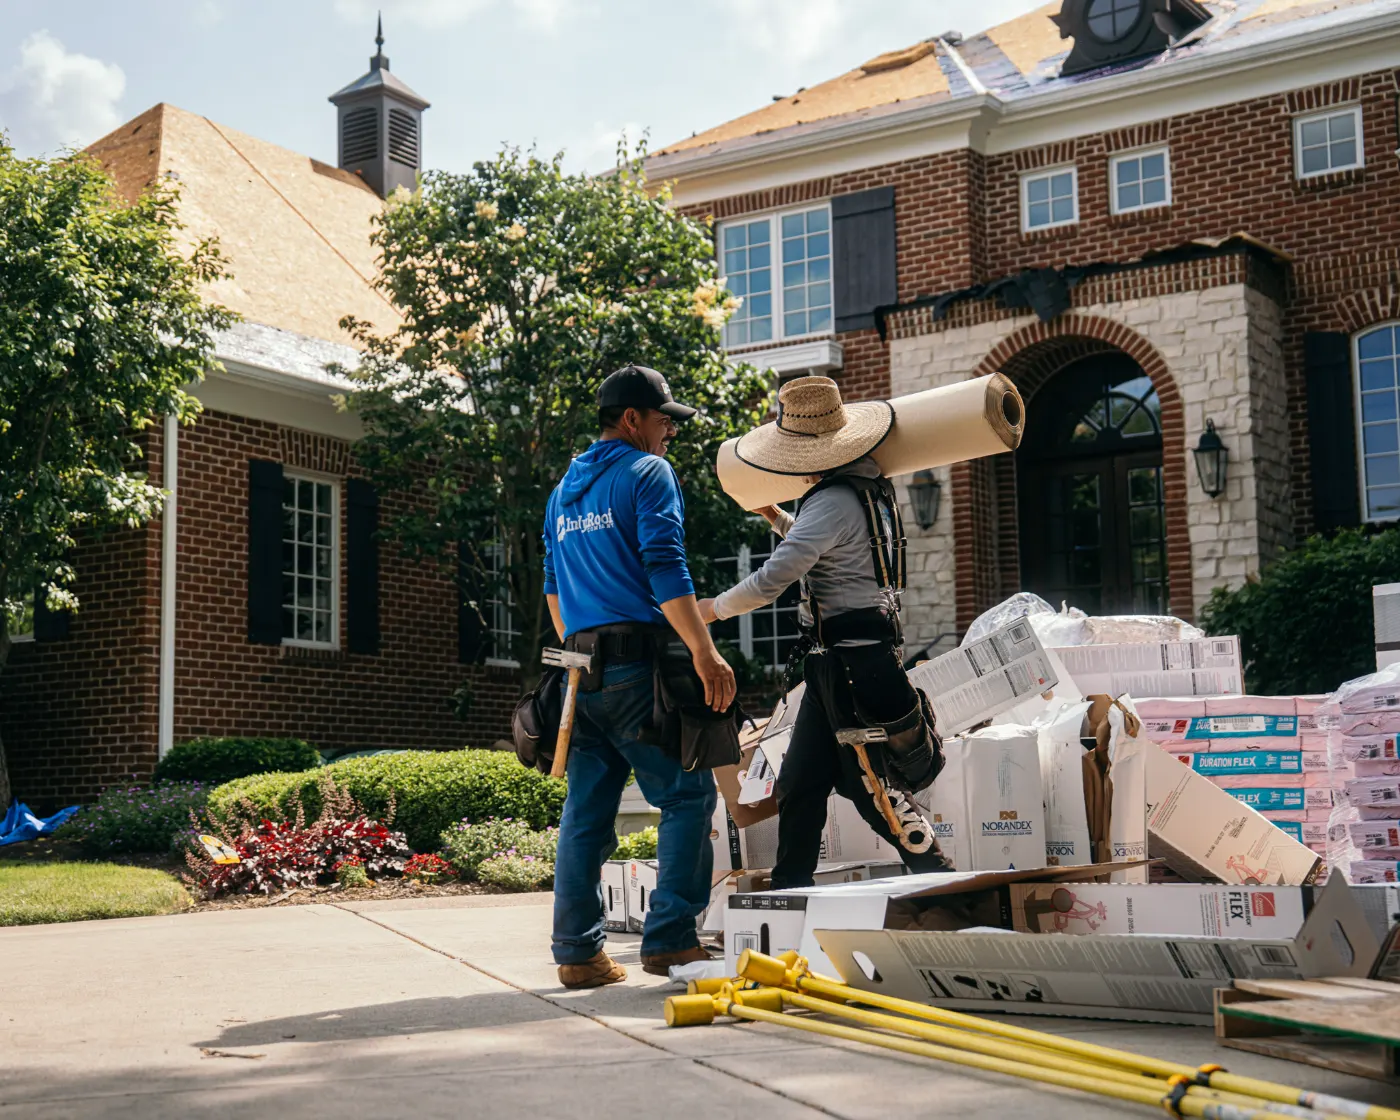
What a New Roof Costs in Wild Air, IN
Some IN carriers offer a credit for Class 4 impact-resistant shingles. The amount is set by the carrier, so confirm it with your agent before the upgrade is priced into a Wild Air quote.
Homeowners in Wild Air choose across four shingle tiers, and the price gap between 3-Tab and Designer/Luxury reflects material weight, wind rating, and warranty depth.
- 3-Tab Shingles: $3-$5+ per sqft
- Architectural Shingles: $4-$8+ per sqft
- Impact-Resistant (Class 4): $5-$10+ per sqft
- Designer / Luxury Shingles: $7-$15+ per sqft
- Residential roofing repair (most jobs): $300 to $2,500+
- Free inspection and written quote
Typical Residential Roofing Costs in Wild Air
Below are per square foot ranges drawn from typical Wild Air market installations. What lands in your final quote depends on roof size, the system, deck condition, pitch, and access.
A plus sign on the upper numbers signals that what the inspection finds may carry your project beyond the listed maximum. Everything here is priced per square foot installed for the Wild Air market in 2026.
Factors That Affect Residential Roofing Cost in Wild Air
Two homes with the same square footage can have very different replacement costs. Here is what changes the number.
Roof Size and System Type
Square footage is the largest single cost driver. 3-tab shingles are the most economical per square foot but have shorter service lives. Architectural shingles are the industry standard for most homes. Class 4 impact-rated shingles command a premium, and in hail markets some carriers offer a credit against that rating; your agent is the one who can price it. Designer / luxury shingles command the highest premium for slate or shake aesthetics.
Deck Condition
Photos come first. Any decking damage found once the tear-off is underway gets documented that way, then added to the scope, then replaced before the new roof goes down. Aging roofs hide this kind of damage often enough that we scope it separately.
Access and Logistics
Material access, landscaping protection, story count, and roof pitch each add to the cost. Where the home is occupied and the household is busy, scheduling has to be handled carefully, which stretches the timeline.
Warranty Target
Extended and lifetime tiers of a manufacturer shingle system warranty come with requirements: particular installation methods, matched components. Homes built to those top tiers run higher than minimum-spec work.
How Homeowners Insurance Works in Wild Air
The claim doesn't wrap up when the adjuster drives off, and it shouldn't really start there either. Damage caused by wind or hail is usually what homeowners insurance steps up for; the wear and age that builds up on a homes over time generally doesn't. A roofing contractor at that meeting is what changes whether damage gets caught.
Wild Air Roofing pulls together photo documentation and a written scope before the meeting ever happens, then adds supplemental paperwork once the claim is moving. From that point on, Wild Air Roofing doesn't step back, keeping the adjuster looped in until the roofing project is done. homeowners usually notice how much more thorough that makes the whole thing.
Payment Options That Work for You
Your Wild Air Roofing project lead will walk you through every financing option during the assessment. Terms in writing, no pressure, no surprise charges.
Pay for your project at a later time, but lock in today's pricing. Ideal for homeowners waiting on insurance settlements.
- No payments for 12 months
- No interest if paid in full
- Lock in current pricing today
Divide your project cost equally across 12 months with zero interest. Most homeowners choose this option for predictable budgeting.
- Equal monthly payments
- 0% interest for 12 months
- Simple, predictable budgeting
Lower monthly payments generally mean a longer runway, and that's the trade this plan makes. A larger roofing project gets spread out with fixed equal payments over more time, so homeowners chasing the smallest monthly number get exactly that.
- Up to 20-year terms available
- Fixed equal payments
- Ideal for larger projects
Financing provided by Slice, Foundation Finance, Regions. Subject to credit approval. Rates, terms, and promotional periods are set by the lender and disclosed in writing before you sign.
Roofing Cost FAQ for Wild Air
Cost-related questions we hear most often from Wild Air homeowners.
Get a Free Inspection
Set up your free roof inspection with no obligation attached. During business hours we answer Wild Air inquiries promptly.